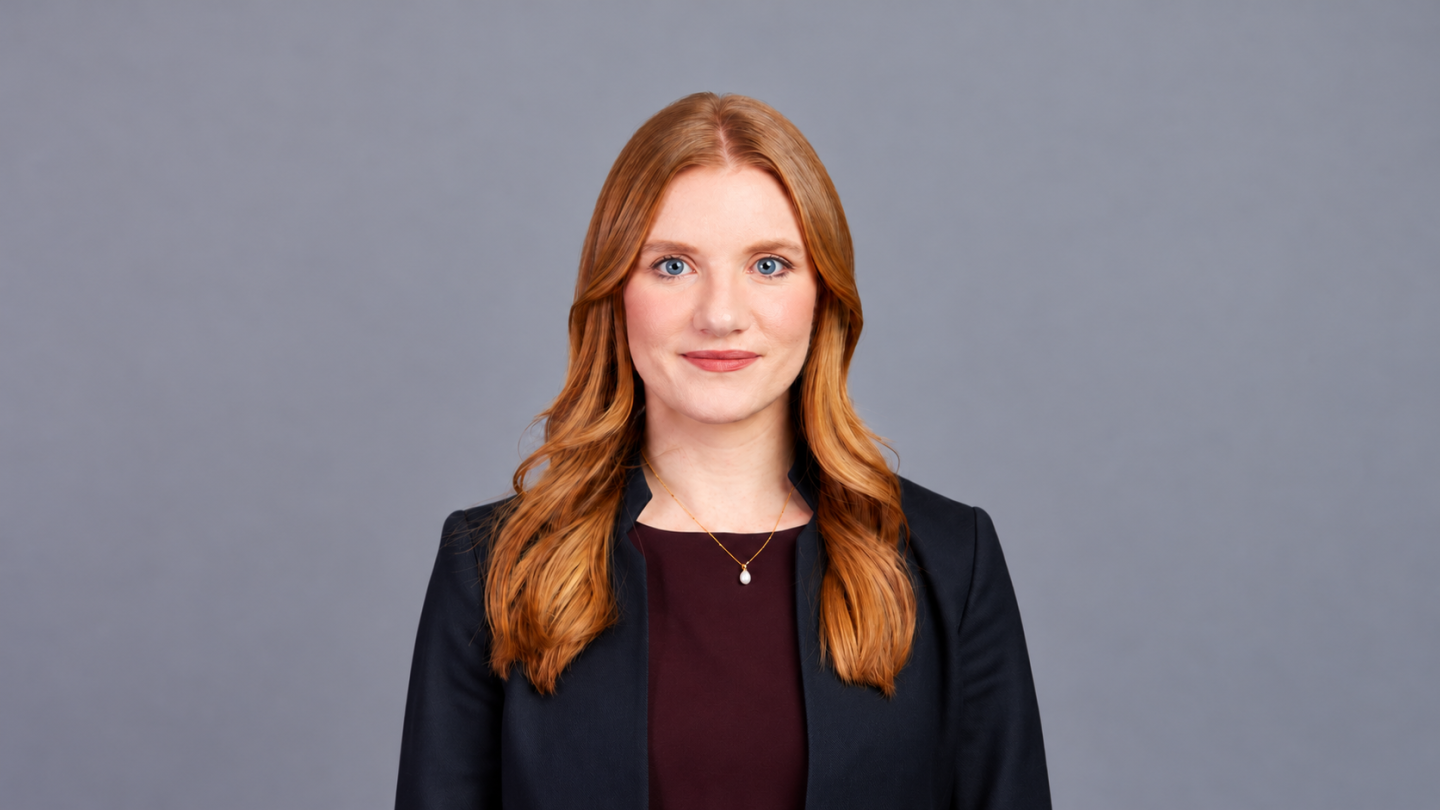
Active ETFs are gaining momentum, as investors seek vehicles that deliver specific portfolio outcomes. J.P. Morgan Asset Management, Europe’s leading provider of active ETFs, sees strong growth in strategies designed to generate income and mitigate downside risks. It’s a trend that Katie Magee, Investment Specialist in US Equities, doesn’t see letting up any time soon.
Derivative income ETFs grew roughly 35% globally over last year. The most successful of its derivative income ETFs in terms of flows was JEPQ, an Equity Premium Income (EPI) active ETF giving exposure to the Nasdaq. It is also the active ETF in UCITS that took the largest YTD flows.
For Katie Magee, Investment Specialist in J.P. Morgan Asset Management’s US Equities Investment Team, there are exciting opportunities in the space, and this growth reflects a broader shift in how investors are thinking about active ETFs. “Active ETFs are a great solution for clients as they help to address specific challenges, ranging from a need to generate alpha above a benchmark, finding more risk managed building blocks that suit the underlying benchmarks, or addressing specific outcomes,” she explains. “Active ETF investing can help people get invested and stay invested.”
Outcome-oriented solutions
The firm divides its active outcome-oriented ETF equity solutions into two broad categories: those that focus primarily on generating income and the hedged equity strategies, which are geared towards mitigating downside risks. Both strategies bring together J.P. Morgan Asset Management’s active insights and a disciplined use of options.
The Equity Premium Income range, as the name suggests, is focused on generating income. As Magee notes, when the strategy was first developed in the US in 2017, the investment backdrop was one in which traditional sources of income were difficult to find: bond yields were at zero, even negative in parts of Europe, while the US market dividend yields weren’t compelling. Meanwhile, areas that could offer higher yield were typically more illiquid.
For J.P. Morgan Asset Management, therefore, “being able to package a strategy that aims to give our clients consistent levels of income in a highly accessible, liquid vehicle was very compelling,” Magee explains. Even while there’s an evolution in terms of market volatility or yields, “income is something that never goes out a of style. It’s a consistent outcome we’re looking to deliver to clients, giving equity exposure with less volatility and that’s why we’ve seen continued demand there,” she adds.
Investor considerations and expectations
Equity Premium Income works well for clients who are willing to give up some of the potential upside of the market in exchange for the consistency of income, Magee notes. Hedged equity solutions, meanwhile, take a different approach and are more explicitly focused on mitigating downside risks.
A central feature of the hedged equity approach is the laddered options overlay, designed to keep investors continuously hedged without needing to make a choice on timing. “Our hedged equity solutions are designed to be a little bit more evergreen because we are constantly laddering and staggering these hedges through time,” she notes. “To us, it doesn’t matter when you invest. You should always expect the same outcome: about half the beta of the market and the majority of the total return. That takes a bit of the market timing element out of the equation for the end client, providing a better longer term solution.”
There are two ETFs available within the hedged equity range : HELO is benchmarked to the S&P 500 Index, HEQQ to the Nasdaq 100. This allows investors to choose between broader US equity exposure or a portfolio focused more on technology and growth.
Similarly, the Equity Premium Income strategies offer different benchmarks: JEIA, for example, follows the S&P 500 Index and uses a bottom-up fundamental active stock selection portfolio, designed to be a bit more defensive than the market. “We then combine that with an options overlay, selling call options on the S&P 500,” Magee explains. “And because we’re selling those call options, it means that we are giving up some of the potential upside of the market but, in exchange, are getting paid premiums that become income we can deliver to clients.”
JEIA is designed to provide a good level of income on an annualized basis, with lower beta and volatility than the index. The Nasdaq 100 strategy (JQPD), meanwhile, has around 80% of the benchmark’s beta and volatility, with a different target yield. “It provides clients with higher income, technology exposure, and less volatility—three aspects you don’t often hear together—and I think that’s why it has been one of our fastest-growing ETFs in the UCITS range.”
Magee doesn’t see the demand among investors for these active ETFs as letting up any time soon. “We think this is a huge opportunity to help investors get invested and stay invested – here volatility is your friend,” she says. “You should expect consistency of income, less volatility in beta than the market—and the role that that plays in a portfolio is really compelling.”
Find out more by visiting our dedicated online pages for EPI and HELO or contacting JPMAM by email: info.benelux@jpmorgan.com.
This is a marketing communication. The views contained herein are not to be taken as advice or a recommendation to buy or sell any investment or interest thereto. Any forecasts, figures, opinions, statements of financial market trends or investment techniques and strategies expressed are, unless otherwise stated, J.P. Morgan Asset Management’s own at the date of this document. They are considered to be reliable at the time of writing, may not necessarily be all inclusive and may be subject to change without reference or notification to you. The value of investments and the income from them may fluctuate in accordance with market conditions and investors may not get back the full amount invested. Past performance and yield are not a reliable indicator of current and future results. There is no guarantee that any forecast made will come to pass. This communication is issued in Europe by JPMorgan Asset Management (Europe) S.à r.l., 6 route de Trèves, L-2633 Senningerberg, R.C.S. Luxembourg B27900, corporate capital EUR 10.000.000.
366200ce-ce4a-11f1-8884-7d0f1d05a300